Because when you’re lifting big, your protection needs to measure up.
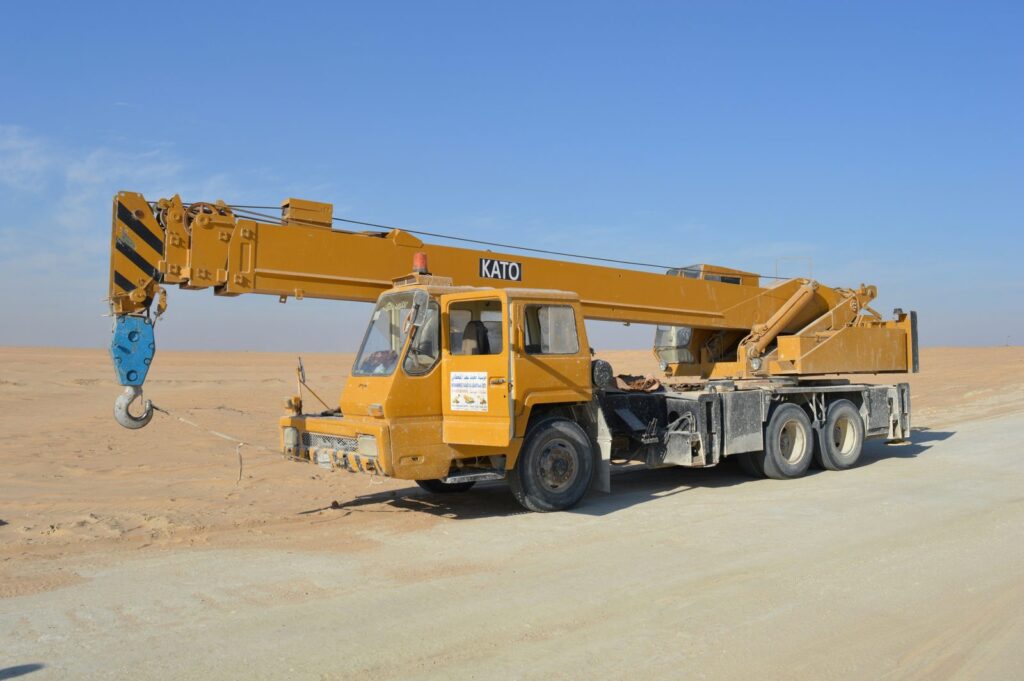
Imagine a mechanical failure causes a boom to drop on site, or your mobile crane slips off an unstable pad during a heavy lift. In an instant, an ordinary job turns into hundreds of thousands of dollars in property damage, third-party liability claims, and an expensive crane sitting completely out of action.
Commercial crane and plant insurance acts as your financial shield, protecting your specialised machinery, site liabilities, and business revenue from severe losses.
As Sydney's leading business insurance brokers, CIG does the heavy lifting for you. We compare policies across Australia's major insurers to find cover that matches how your crane business actually operates at height, on hire and under contract with no gaps.
Partner with CIG’s insurance brokers and lock into the right protection today.
Crane Insurance pays for the fallout when a lift goes wrong. From a dropped load or a tipped boom to a blown motor or road crash, it covers your rigs, your liabilities, and your revenue so one site accident doesn't sink your business.
Standard business policies typically exclude working at height, making this tailored coverage essential. A typical crane insurance policy bundles together:
If you own, lease or operate cranes for a living, a standard business insurance policy won't cut it. General trade cover rarely accounts for the actual risks crane operators face: rigging failures, load drops, boom strikes, transport damage and third-party property claims that can run into the millions.
You need cover built around how cranes actually work on site, in transit and during maintenance. That's where we come in. Below are the crane businesses we insure at CIG.
• Mobile crane hire companies (wet hire and dry hire)
• Tower crane operators and erection crews
• Crawler crane contractors
• Franna and pick-and-carry crane operators
• Mini crane and spider crane hire
• Overhead and gantry crane operators
• Crane rigging and dogman crews
• Heavy lift and project cargo contractors
• Crane transport and float operators
• Crane maintenance and inspection services
• Bridge and beam erection contractors
• EWP, cherry picker and boom lift hire companies
• Telehandler and rough terrain forklift operators
Third-party property damage and bodily injury claims carry catastrophic financial exposure, leaving you vulnerable to litigation and poor business relations. Public liability covers legal defence costs, medical bills and third-party repair costs to safeguard your business.
Machinery loss not only halts high-value contracts, but also places financial pressure on your cash flow while daily hire costs accumulate. A sudden structural failure or accidental tip-over could severely damage your crane’s boom mid-operation. Plant and equipment coverage reimburses the repair or replacement value of your rig, keeping your operational fleet active.
Imagine a rented crane suffers catastrophic damage while under your care, or a suspended load slips, causing total loss to the payload. You face severe contract penalties, huge replacement invoices from hire yards, and lasting reputational harm with the contractors you work with. Hired plant and transit coverage pays for hired equipment damages, protecting your bottom line.
We start by listening. Whether you run a single mobile crane or operate a tower crane fleet, we map out your load capacities, hook risks, site environments, and high-risk lifting activities.
We present your risk profile to Australia’s specialist heavy plant and liability underwriters, leveraging market access to compare tailored machinery, transit, and public liability options against cost.
Standard policies leave dangerous gaps. We calibrate your plant values and structure specific hook liability, dry-hire extensions, and road transit limits to ensure your assets are fully protected without overpaying.
Unlike traditional brokers, we don't disappear once the policy is placed. When an incident occurs on site, we manage your claim directly with assessors. As your fleet expands, high-risk projects arise, or crew sizes shift, we adapt your coverage to stay aligned.
Ready to get started? Get in touch with a CIG broker today.
A broker unlocks market options and better rates you can’t get on your own, saving you money for the long haul. Better yet? When you have a claim, we do the heavy lifting, dealing with the insurer directly and advocating for your payout.
Better options. Zero hassle. Your personal insurance ally.
Choosing a broker for crane insurance is really choosing who's in your corner when something goes wrong. That's why Australian businesses trust CIG with choosing the optimal insurance for them.
No call centres, no cookie-cutter policies. We tailor every policy to the way your business actually operates.
When a crane overturns, hook liability is triggered, or an expensive load suffers damage in transit, we don't hand you a phone number. We step in immediately, manage the claims process directly with heavy-plant assessors, and advocate aggressively for your best financial outcome.
Led by Director Jeff Tyler, our individually authorised brokers draw on deep industry experience and strong insurer relationships to find the most suited, cost-effective cover for businesses across Sydney and surrounding NSW.
You’ve got questions about protecting your business. We have the expert answers.
On-hook liability protects against physical damage to a customer's load or materials while suspended by your crane. Standard public liability excludes items under your care, custody, or control, making this specific coverage essential during active lifts.
Yes. Wet hire insurance covers operations where you supply both the crane and your own certified operator. Dry hire insurance covers risks when renting equipment out to external third parties who operate the machinery themselves.
Standard plant policies only cover on-site operations. Driving mobile cranes on public roads requires dedicated commercial heavy vehicle or road risk cover to protect against road accidents, third-party collision damage, and CTP claims while in transit.
CIG is part of the Steadfast Network, which means clients get access to broader policy wordings and products you won’t find on retail comparison sites. More importantly, we back clients not just at policy setup but through claims, renewals, and those moments where you need to focus on growing your business. Whether you require a detailed assessment of your current cover or clear, informed guidance on your insurance needs, our team is ready to support you.
Keep your business moving, no matter what happens on the lift or on site.
Your heavy plant and operators are the engine of your cash flow. One overturned rig, hook liability dispute, or expensive drop load shouldn't bring your operations to a standstill. With tailored heavy-machinery protection built around how you actually work, CIG keeps your fleet covered, compliant, and moving forward.
Speak to an experienced CIG insurance broker today and lock in the right cover for your business.